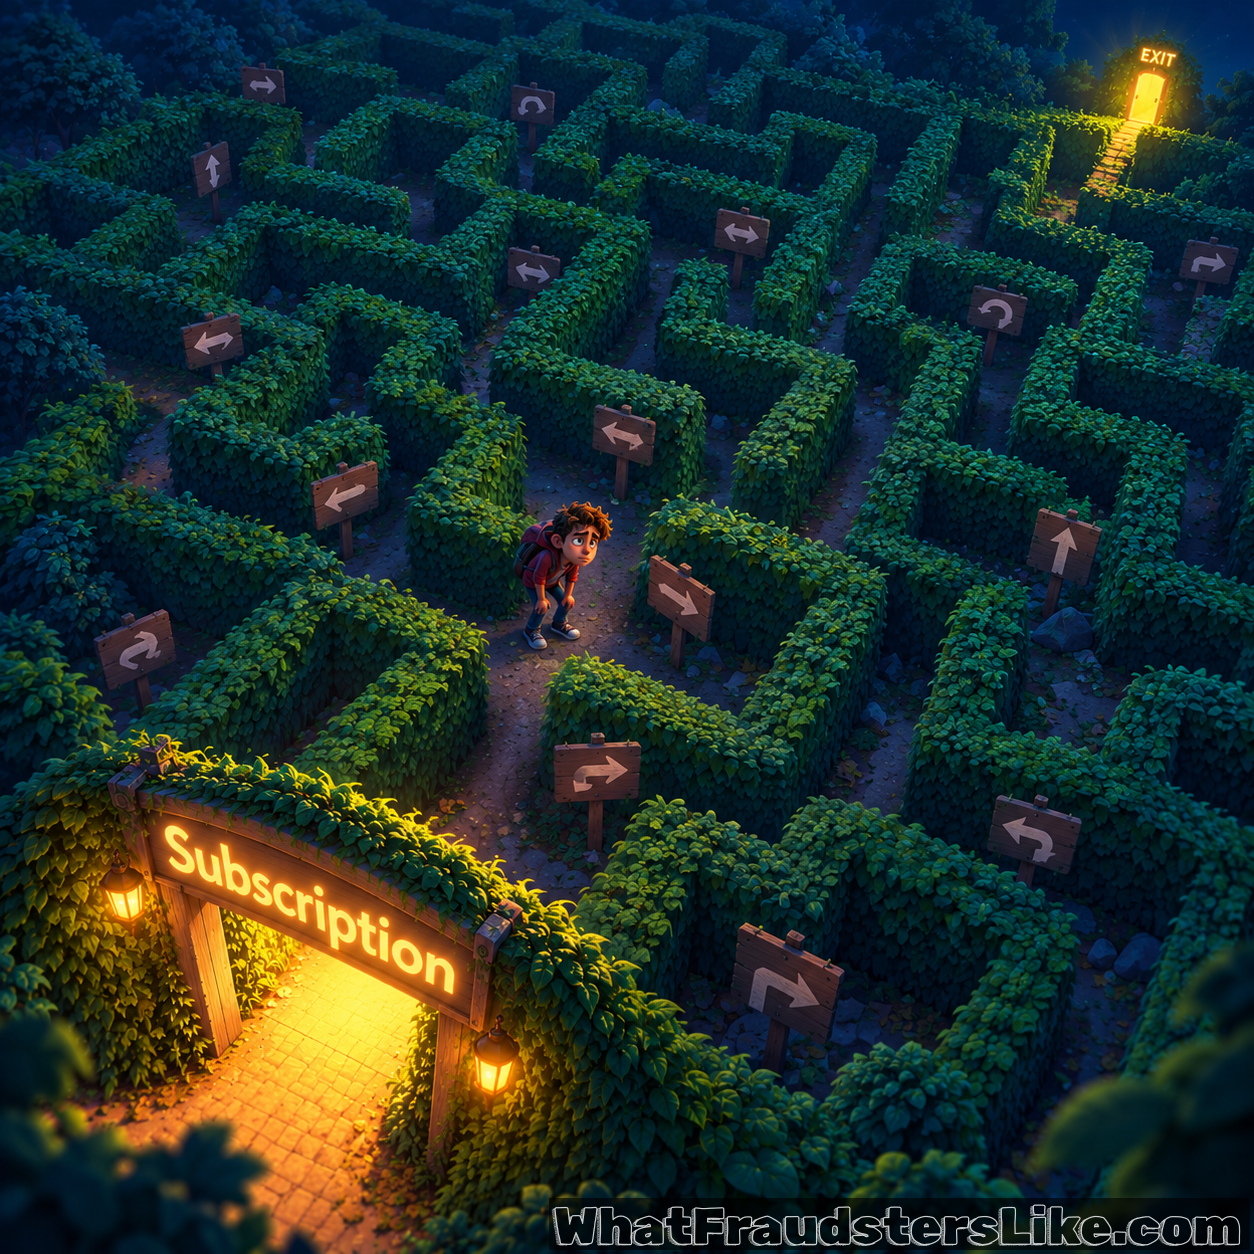
A misleading trial offer collects card details and starts recurring charges that the customer did not expect.
Subscriptions are handy when the price, the frequency and the way out are all clear. Dishonest businesses and scammers use the same recurring-payment setup to turn confusion, inertia and long-forgotten consent into steady income.
How subscriptions get abused:
🎁 The "free" trial - A cheap sample, a small delivery fee or an introductory offer collects your card details. The advertising says free, while the terms set up a monthly charge.
🪤 Sign-ups in disguise - Pre-ticked boxes, misleading buttons and crowded checkout pages make a subscription look like a one-off purchase or an optional extra.
🧱 Cancellation obstacle courses - Canceling can mean hidden menus, repeated calls, retention scripts or a process that never confirms you are out.
🔔 Fake renewal notices - Scammers pose as familiar streaming, antivirus, cloud or membership services. The "subscription expiring" or "payment failed" message leads to stolen logins, stolen card details or a remote-access scam.
🥷 Charges that blend in - Small recurring amounts, unfamiliar billing names and shifting payment dates go unnoticed, because the amount looks about right and nobody checks who took it.
🔄 Abuse from the other side - Some customers use up digital content or services, then dispute recurring payments they genuinely authorized. That chargeback abuse shifts the loss, and the cost of proving it, onto honest merchants.
In September 2025, Chegg agreed to pay $7.5 million to settle FTC allegations that it made canceling difficult and kept charging after customers asked to cancel.[ref] Visa's policy for subscription merchants offering free trials or introductory deals sets requirements for consent, disclosure, reminders and online cancellation within that scope.[ref]
What to do:
For consumers:
- Before entering card details, note the price after the trial, how often you will be charged and how to cancel.
- Set a reminder before the trial ends, and check your card and bank statements every month.
- Cancel through the service's official app or website, keep the confirmation and check the next statement.
- Treat unexpected renewal or payment-failed messages as untrusted. Open the service yourself instead of using the link or phone number provided.
- Dispute unauthorized charges, or charges after cancellation, quickly. Do not dispute a service you knowingly bought and used.
For merchants and financial institutions:
- Get explicit consent, and show the price, frequency and renewal terms right next to the button that signs the customer up.
- Make canceling as easy to find and as reliable as signing up, and confirm it immediately.
- Use billing names customers recognize, and send reminders before renewals.
- Keep evidence of consent, usage, notifications and cancellation, and watch merchants with unusual complaint or dispute patterns.